

Get breaking business news on WhatsApp
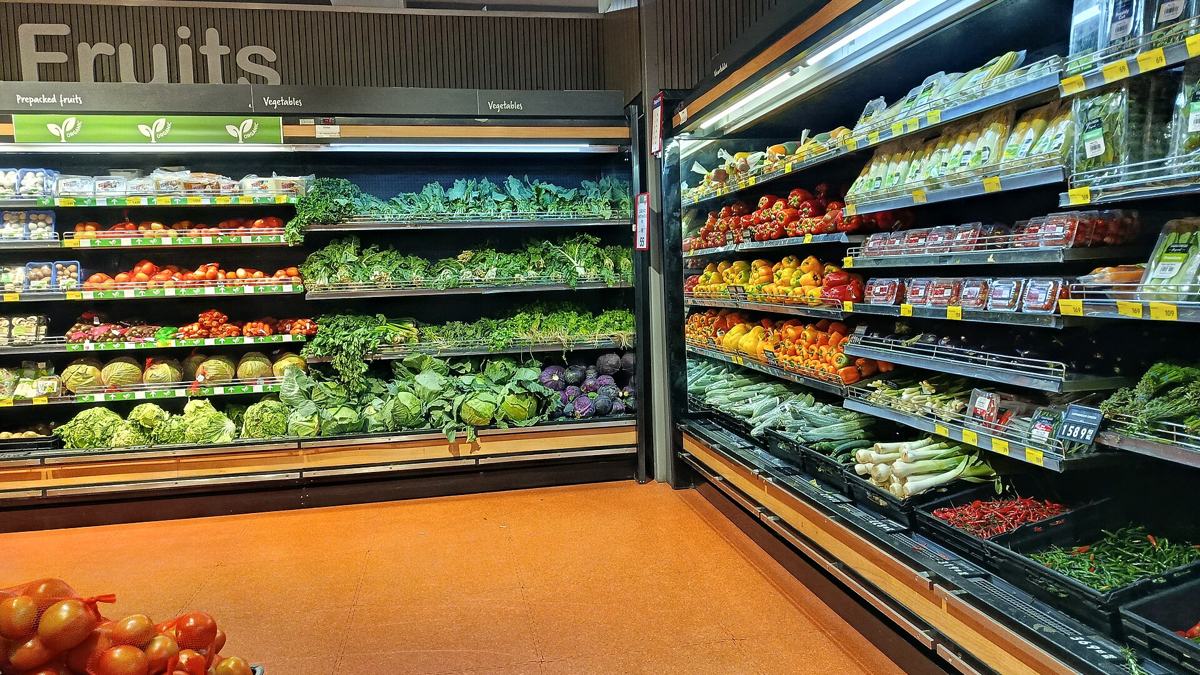
Three supermarket chains take about 60% of the money Kenyans spend in modern grocery stores, according to estimates published by Quickmart as part of its share sale on the Nairobi Securities Exchange.
The Quickmart PLC information memorandum cites Sagaci Research’s Kenya Retail Market Update. It puts Naivas well ahead with more than 31% of modern grocery sales by estimated revenue in 2025. Quickmart is second with about 15% and Carrefour third with about 14%. Magunas has 6% and Foodplus 4%, while the remaining 29% is shared among other operators.
“The Kenyan modern grocery retail market is concentrated among a small number of leading chains that together make up 60% of the market, and the remaining market share is fragmented across a long tail of smaller operators,” the document says.
Quickmart is offering 2 billion ordinary shares at KSh7.50 each. The offer opened on October 5 and closes at 5pm on October 30.
A small slice of a big market
The memorandum puts Kenyan household spending at KSh13.5 trillion, the retail market at KSh3 trillion and modern retail at KSh0.4 trillion. That means formal chains make up about 12% of total retail sales.
In groceries alone, modern trade penetration is estimated at 24%. The document compares this with 44% in Saudi Arabia, 64% in South Africa, Mexico and Turkey, and 71% in Brazil. Informal traders still dominate. The document says they offer credit in some communities, flexible pack sizes and price points, and fresh food through open-air markets and neighbourhood outlets.
Kenya’s modern chains run about 500 outlets across roughly 20 retail chains. The memorandum says the number of modern retail stores rose from 339 in 2020 to 520 in 2025. Newer entrants include discount chain Jaza, China Square and Panda Mart.
How the market got here
By 2023, six relatively large retailers had left the market, and other operators took over their assets. They included Nakumatt and Tuskys, which at their peak had 65 and 64 stores, as well as South Africa’s Shoprite and Botswana’s Choppies.
The memorandum says the collapse of the two local chains has been “widely attributed to weak corporate governance, overly aggressive expansion strategies and inadequate cost control.” It says foreign operators struggled with rents charged in foreign currency at premium sites, costly expatriate managers and ranges skewed towards higher-priced imports.
Where the fight is now
Competition is most intense in Nairobi and its suburbs, while regional towns “remain comparatively underserved,” according to the document. It says low vehicle ownership, limited storage space and sensitivity to transport costs have pushed the trade towards smaller neighbourhood supermarkets and express stores instead of large mall outlets. Shoppers prefer weekly trips to monthly or occasional bulk buying.
Quickmart’s own sales reflect this. Supermarkets brought in 49% of its revenue in 2025, up from 43% in 2021. The company had 68 stores in 16 counties at the end of June 2026 and opened four more in July and August, taking it to 72. It plans to reach 125 stores in Kenya by 2030, paid for mainly from cash generated by the business.
The market share figures are estimates. Quickmart’s intention to float announcement says such data “should be treated with caution” and has not been audited or independently verified.
Investors weighing the offer can compare the company’s pitch with an analyst’s view that puts Quickmart’s fair value below the IPO price. Our earlier reports cover IFC’s anchor commitment and the fees paid to the deal’s advisers.
Prefer WhatsApp? Follow Business Radar on WhatsApp
Weekly, free. We only use your email for this newsletter and you can unsubscribe in one click. Privacy policy.