

Lawmakers have opened a review of Kenya’s buy now pay later (BNPL) and asset finance lenders after receiving 110 complaints from borrowers, some of whom say they paid back up to four times what they borrowed.
The National Assembly’s Finance and National Planning Committee, chaired by Molo MP Kuria Kimani, said on Thursday it will require firms in the sector to show that they comply with consumer protection rules.
“The Committee is in receipt of several complaints from victims of exploitation. As we move to review the regulatory safeguards governing the sector, we will require all firms in this sector to demonstrate to the Committee that their operations strictly follow the laid down safeguards,” Kimani said.
Mogo Auto skips meeting
Motorcycle and vehicle financier Mogo Auto Limited had been invited to appear on Thursday but did not attend and asked for the session to be rescheduled, the committee said.
“Recently, the Committee received representations from various stakeholders detailing their experiences within the sector. This is why we had invited Mogo Auto to shed light on the matter. They, however, requested the meeting to be deferred. We will not hesitate to invoke the provisions of Standing Order 191 to ensure that all firms invited to shed light on this matter honour the invitations,” Kimani said.
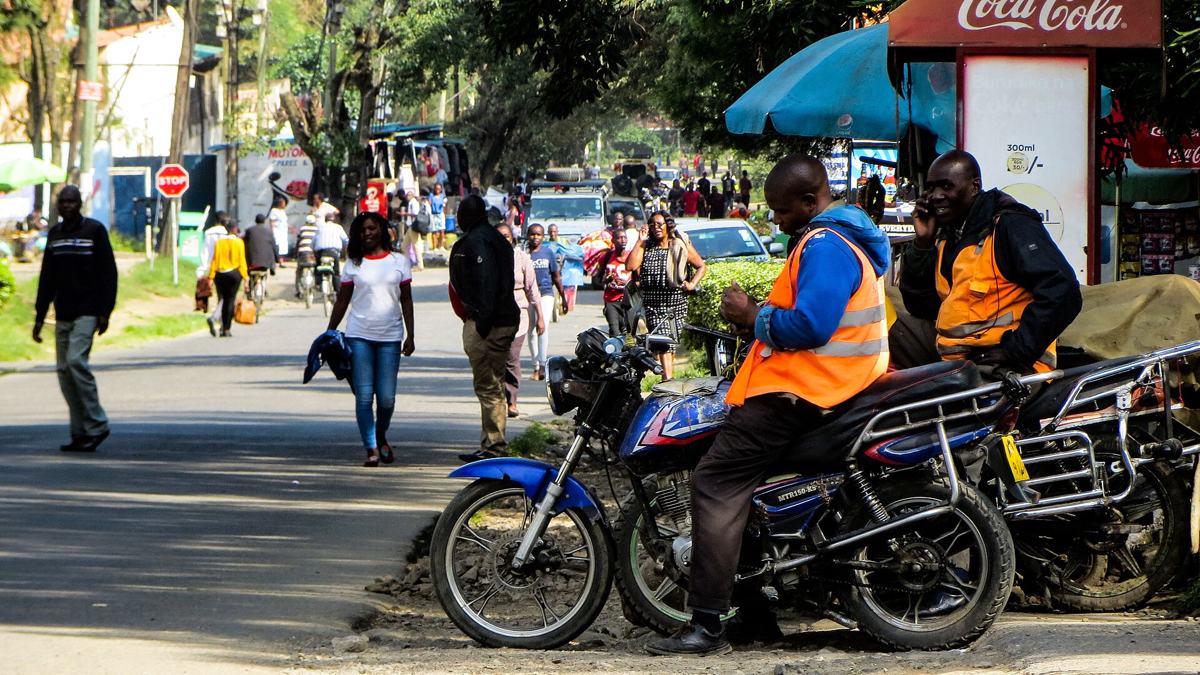
The committee has set November 5 to hear from lenders named in a petition filed by several boda boda riders, The Star reported.
Loans repaid three or four times over
Kimani said the complaints include borrowers who paid two to four times the original loan amount without clear disclosure of the credit terms.
“We have continuously, since the start of this inquiry, received numerous other complaints where there is no disclosure of the loan amount, and some customers have paid even three or four times the loan amount,” he said.
MPs will look at the firms’ financing products, customer onboarding, licensing status and compliance with Central Bank of Kenya (CBK) requirements. They will also review account handling, payment records, arrears notices, repossession of assets, the sale of recovered property and how sale proceeds are applied to outstanding loans.
Complaint handling, customer redress and the conduct of agents and third-party service providers are also on the list. The committee is expected to meet the CBK to assess how the sector is regulated.
Gaps despite 2024 law
The Business Laws (Amendment) Act, 2024 brought non-deposit-taking credit providers under CBK oversight. Kimani pointed to the in-duplum rule, which caps the interest that can be recovered on a qualifying non-performing loan at the outstanding principal.
“No lender should be allowed in Kenya to lend beyond or outside the legal framework,” he said, adding that the committee will table a report in the House to pave the way for legal or regulatory action where violations are found.
In July 2026, the Competition Authority of Kenya warned that gaps in the law governing digital lenders were exposing borrowers to hidden fees, predatory lending and coercive debt recovery.
Asset financing is widely used by small businesses and informal workers, including boda boda operators, to buy the motorcycles and equipment they earn a living from.