

Get breaking business news on WhatsApp
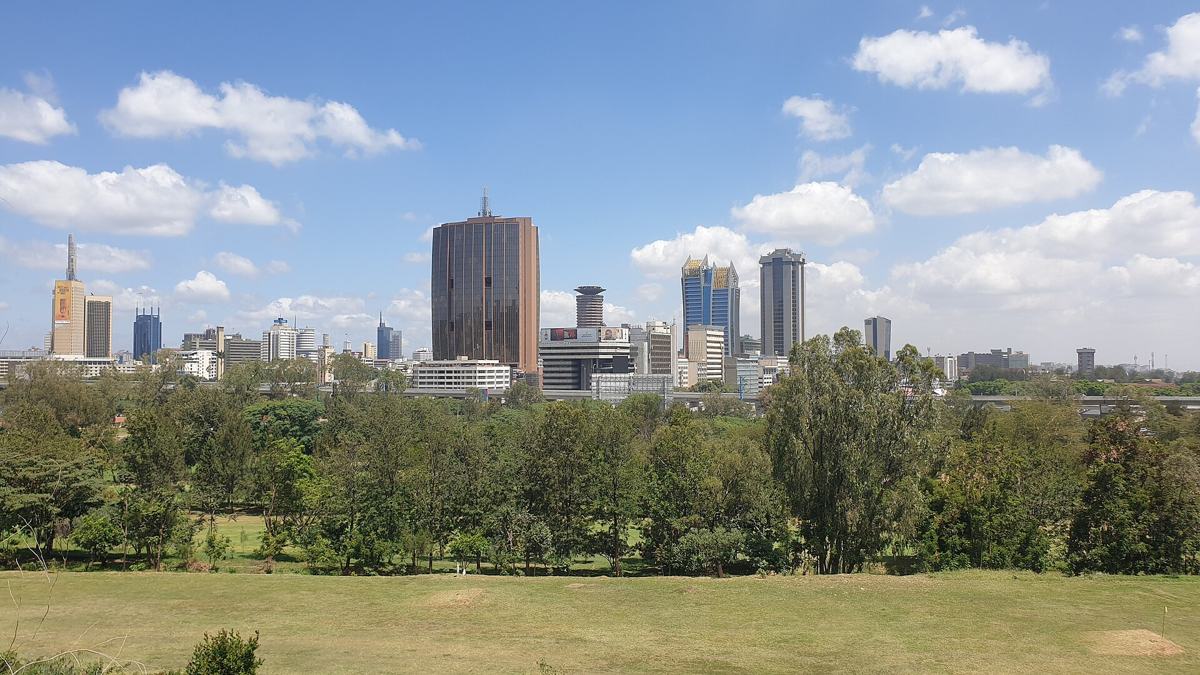
Kenyan shares had a rough week. The Nairobi Securities Exchange (NSE) All Share Index (NASI) fell 4.56% in the week to October 22, according to the Central Bank of Kenya’s weekly bulletin released on Friday, while the shilling eased slightly to KSh129.91 against the US dollar.
The narrower indices fell far less. The NSE 25 slipped 0.51% and the NSE 20 lost 0.39%. Total market capitalisation dropped 0.38% to KSh3.996trn from KSh4.011trn a week earlier.
A big block trade lifted turnover
CBK said a sharp rise in shares traded and equity turnover during the week came from a single block trade of 4.5 billion shares worth KSh42.5bn. That matches the deal in which Aliko Dangote’s group bought 24.76% of Kenya Pipeline Company, executed on October 19. KPC shares have since climbed to a record (our report on the KPC rally).
The gap between a 4.56% fall in NASI and a much smaller fall in total market value reflects how the indices are built and which large stocks moved. NASI covers all listed shares, so heavy moves in big counters weigh on it most.
Shilling drifts weaker as reserves hold
The shilling traded at KSh129.91 to the dollar on October 22, compared with KSh129.81 a week earlier. The move is small, but it continues a slow slide: the currency was at about KSh129.41 in early August.
Usable foreign exchange reserves rose by US$4m to US$14.693bn, equal to 5.9 months of import cover. That is comfortably above CBK’s statutory minimum of four months, but about US$349m below the US$15.042bn recorded on September 24.
T-bill rates edge lower
At the October 22 Treasury bill auction, investors bid KSh28.8bn against KSh28bn offered, a 103% subscription rate. Demand was lopsided: the 91-day bill drew KSh14.34bn against KSh8bn on offer, while the 182-day and 364-day papers each drew less than the KSh10bn offered.
- 91-day: 8.748%, from 8.750%
- 182-day: 8.859%, from 8.860%
- 364-day: 9.027%, from 9.038%
Money markets were liquid. Banks held average excess reserves of KSh32.1bn above the 3.25% cash reserve requirement, and the overnight interbank rate (KESONIA) stayed at 8.75%, in line with the Central Bank Rate. Average daily interbank trading rose to KSh19.8bn from KSh14.9bn.
Debt and oil
Gross domestic debt stood at KSh7.822trn on October 16, of which KSh6.501trn was in Treasury bonds and KSh1.215trn in bills. Yields on Kenya’s Eurobonds rose by an average of 2.17 basis points. On global markets, Murban crude rose to US$108.23 a barrel, a reminder that fuel import costs remain the main pressure on the shilling.
For earlier readings, see our previous shilling and T-bill report. Savers weighing bills against money market funds can use our comparison guide.
The picture for the coming weeks is mixed. Stable short-term rates and ample bank liquidity point to steady T-bill yields, and CBK has reopened two long-dated bonds worth KSh50bn with bids due on November 4 (how to bid). On the other side, high oil prices and slowly falling reserves keep the shilling under mild pressure, and equity investors have been cautious. Readers who hold shares through unit trusts or pension schemes will see the weaker index reflected in their next statements, though one bad week says little about long-term returns.
Prefer WhatsApp? Follow Business Radar on WhatsApp
Weekly, free. We only use your email for this newsletter and you can unsubscribe in one click. Privacy policy.