


Updated 10 November 2026
This free rent vs buy calculator compares two paths for the same home in Kenya. In one, you buy with a mortgage and pay stamp duty, fees and running costs. In the other, you rent a similar home and invest the cash you would have spent on the deposit and the extra monthly cost. It shows which path leaves you with more wealth after the number of years you choose.
The calculator runs in your browser and saves nothing. The default mortgage rate of 13.6% sits among the large-bank averages on the KBA Total Cost of Credit portal, checked on 10 November 2026; change any input to match your quote.
On this page
Rent vs buy calculator
Estimates only. The calculator ignores tax relief, selling costs and changes in your mortgage rate. Defaults are examples, not forecasts: replace them with your own quote and rent.
How the rent vs buy calculator works
Buying. You pay the deposit plus stamp duty and other fees upfront. Each month you pay the mortgage, worked out with the standard reducing-balance formula, plus owner costs such as service charge, insurance and repairs. At the end, your wealth is the home’s value, grown at the rate you enter, minus the loan still owed.
Renting. You keep the upfront cash and invest it at the return you enter. Each month, if buying would have cost more than rent, the renter invests the difference; if rent is higher, the renter draws down instead. Rent rises once a year at the rate you set. At the end, your wealth is that investment pot.
The result compares the two and shows the first month, if any, when the buyer’s equity overtakes the renter’s pot.
Assumptions you can change
Every input in the rent vs buy calculator can be edited: the price, deposit, mortgage rate and term, stamp duty, fees, monthly owner costs, rent, yearly rent increase, yearly home price growth, savings return and the number of years you want to compare. Start with a quote from your bank and a real rent for a similar home in the same area. Then try a cautious case, with lower price growth and a higher rate, and an optimistic one. If buying only wins in the optimistic case, treat that as a warning sign.
Worked example: a KSh 8 million flat
Take a KSh 8 million apartment with a 10% deposit, a 20-year mortgage at 13.6%, 4% stamp duty, 2% legal and other fees, KSh 6,000 a month in owner costs, rent for a similar flat of KSh 55,000 rising 5% a year, house prices rising 4% a year and an 8% return on savings.
- Monthly mortgage payment: about KSh 87,450.
- Cash needed upfront: KSh 1,280,000.
- After 10 years, the buyer’s equity is about KSh 6.12 million and the renter’s pot about KSh 7.51 million, so renting leaves you about KSh 1.39 million better off.
- Over 20 years the answer flips: the buyer ends about KSh 4.16 million ahead, overtaking the renter in month 182.
Change one assumption and the picture moves a lot. At a 9% mortgage rate, close to the lowest bank average on our mortgage rates in Kenya page, the buyer is about KSh 3.30 million ahead after 10 years and pulls ahead in month 31. If similar flats rent for KSh 80,000 a month, buying wins by about KSh 4.10 million over 10 years.
What changes the answer most
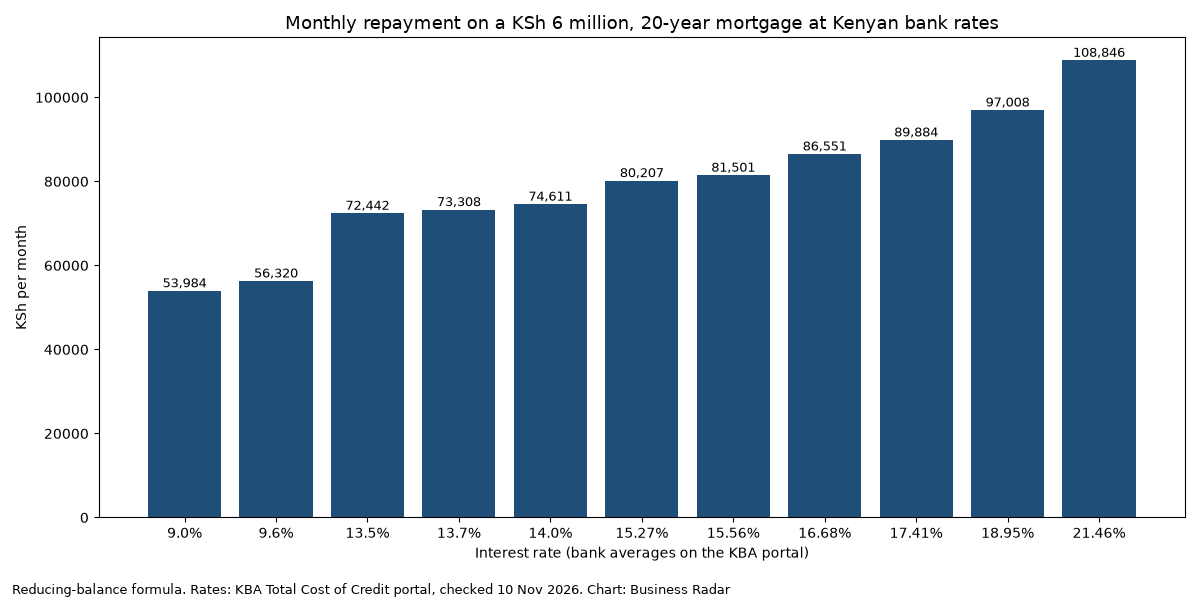
- The mortgage rate. Average bank mortgage rates range from about 9% to above 20%. Each point adds thousands to the monthly payment. Get real quotes before you rely on the result.
- Rent compared with price. If yearly rent is a small share of the price, renting usually wins. HassConsult’s Q3 2026 index shows rents rising faster than asking prices in the suburbs, which narrows that gap. See the Nairobi property price index.
- How long you stay. Stamp duty and fees are paid once, so buying gets better the longer you stay.
- Price growth. In many satellite towns asking prices fell over the year to September 2026, while some suburbs rose more than 10%. Use a growth rate that fits the area.
- Your discipline. Renting only wins if you really invest the difference every month.
The calculator leaves out a few things that can matter: mortgage interest relief from KRA, which our relief guide explains; tax on investment returns; and selling costs. Stamp duty is set at 4% for homes in a municipality and 2% elsewhere; check the exact transfer costs with our land transfer cost calculator, and the repayment schedule with the mortgage calculator. For the full process see how to get a mortgage in Kenya.
More tools and data are on our Kenya real estate hub.
Frequently asked questions
Is it better to rent or buy a house in Kenya?
It depends on the mortgage rate, the rent for a similar home, how long you will stay and how prices move. At a 13.6% rate, our example shows renting ahead after 10 years but buying ahead after 20. At 9%, buying is ahead within three years.
Does the rent vs buy calculator include stamp duty?
Yes. Choose 4% for property in a municipality or 2% for other areas, and add legal, valuation and other fees as a percentage of the price.
What return should I use for savings?
Use a return you can actually earn after costs, such as a money market fund or Treasury bill rate. A higher return makes renting look better.
Does the calculator save my numbers?
No. It runs in your browser and nothing you enter is sent to Business Radar.
Prefer WhatsApp? Follow Business Radar on WhatsApp
Weekly, free. We only use your email for this newsletter and you can unsubscribe in one click. Privacy policy.

