Get breaking business news on WhatsApp
Prime Bank made a profit after tax of KSh5.27 billion in the nine months to 30 September 2026, up 26% from KSh4.18 billion a year earlier, according to unaudited statements the lender published on its website on 16 November. The Prime Bank results show profit before tax rising 26.9% to KSh5.57 billion, helped by higher income from government securities and a 35.6% drop in charges for bad loans.
At group level, which includes the bank’s subsidiaries, profit after tax rose 22.4% to KSh5.39 billion from KSh4.40 billion. Earnings per share for the bank came to KSh792, up from KSh629.
On this page
Where Prime Bank's profit came from
Net interest income rose 15.6% to KSh8.06 billion, from KSh6.98 billion. The gain came mostly from cheaper funding and a bigger bond book rather than from lending:
- Interest earned on government securities rose 11.8% to KSh9.62 billion, from KSh8.61 billion.
- Interest earned on loans fell 9.2% to KSh5.01 billion, from KSh5.52 billion, as lending rates eased.
- Interest paid on customer deposits fell 7.5% to KSh7.66 billion, from KSh8.28 billion.
Non-interest income in the Prime Bank results grew 26.7% to KSh1.59 billion. Dividend income of KSh627.3 million was the largest part, ahead of fees and commissions of KSh519.6 million and foreign exchange income of KSh224.0 million. Loan loss provisions fell to KSh230.1 million from KSh357.4 million,.
The third quarter alone was the strongest in the Prime Bank results so far this year. Profit after tax for July to September was about KSh1.92 billion, against KSh1.58 billion in the second quarter and KSh1.77 billion in the first, based on the bank’s quarterly figures.
Loans, deposits and the balance sheet
The Prime Bank results show net loans to customers up 12.5% from a year earlier at KSh63.20 billion, while customer deposits grew 9.7% to KSh172.50 billion. Total assets stood at KSh249.27 billion, up 7.4% on September 2025 but down from KSh273.93 billion at the end of December 2025.
The balance sheet shrank this year because the value of the bank’s available-for-sale investments fell. They dropped to KSh76.09 billion from KSh94.25 billion in December, and the bank booked a KSh27.16 billion loss in other comprehensive income for the nine months. Revaluation reserves fell to KSh37.70 billion from KSh65.01 billion, cutting shareholders’ funds to KSh74.75 billion from KSh100.04 billion in December.
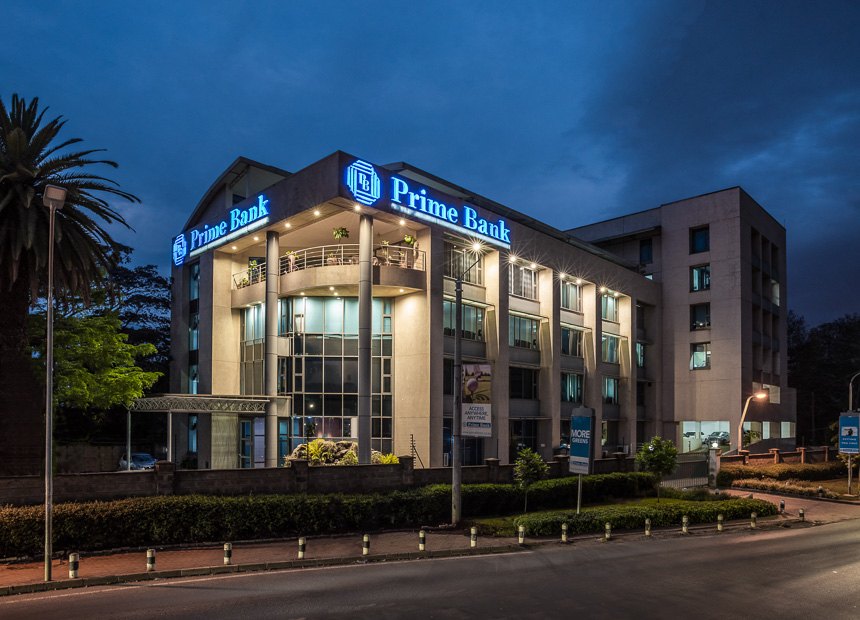
For how the bank compares with a larger rival on loan pricing, see our Prime Bank vs Standard Chartered comparison.
Bad loans, capital and liquidity
In the Prime Bank results, gross non-performing loans rose to KSh5.56 billion from KSh5.32 billion a year earlier. After interest in suspense, provisions and security values, Prime Bank reports zero net exposure on its bad loans.
The Prime Bank results put core capital at KSh31.93 billion, giving a core capital to risk-weighted assets ratio of 29.2%, against the Central Bank of Kenya minimum of 10.5%. Total capital to risk-weighted assets was 30.5%, against a 14.5% minimum. The liquidity ratio was 75.6%, against a 20% minimum.
Loans and facilities to directors, shareholders and associates rose to KSh9.07 billion from KSh5.85 billion a year earlier. Other banks reporting this month include Paramount Bank and Co-operative Bank. For current government paper rates, see the latest T-bill auction results.
Frequently asked questions
What do the Prime Bank results show?
The Prime Bank results for the nine months to 30 September 2026 show profit after tax of KSh5.27 billion, up 26%, with loans up 12.5% and deposits up 9.7%.
How much profit did Prime Bank make in 2026?
According to the Prime Bank results, the bank made a profit after tax of KSh5.27 billion in the nine months to 30 September 2026, up 26% from KSh4.18 billion. Group profit was KSh5.39 billion.
Why did Prime Bank’s profit rise?
Interest on government securities rose 11.8% to KSh9.62 billion, deposit costs fell 7.5% and loan loss provisions dropped 35.6%, lifting net interest income by 15.6%.
Is Prime Bank well capitalised?
Yes. Its core capital ratio was 29.2% and total capital ratio 30.5%, well above the CBK minimums of 10.5% and 14.5%.
Related: Family Bank results: nine-month profit jumps 69% to KSh6.1bn
Prefer WhatsApp? Follow Business Radar on WhatsApp
We will email you a weekly money and business brief. We store your email (and your name, if you give one) for that purpose, under the Kenya Data Protection Act, 2019. You can unsubscribe at any time. Privacy policy.