


Get breaking business news on WhatsApp
In a fresh transfer pricing ruling, the Tax Appeals Tribunal has set aside KSh41.9 million in tax that the Kenya Revenue Authority (KRA) had confirmed against EQ Enabling Qapital Kenya Ltd, the Nairobi branch of Swiss impact investor Enabling Qapital AG.
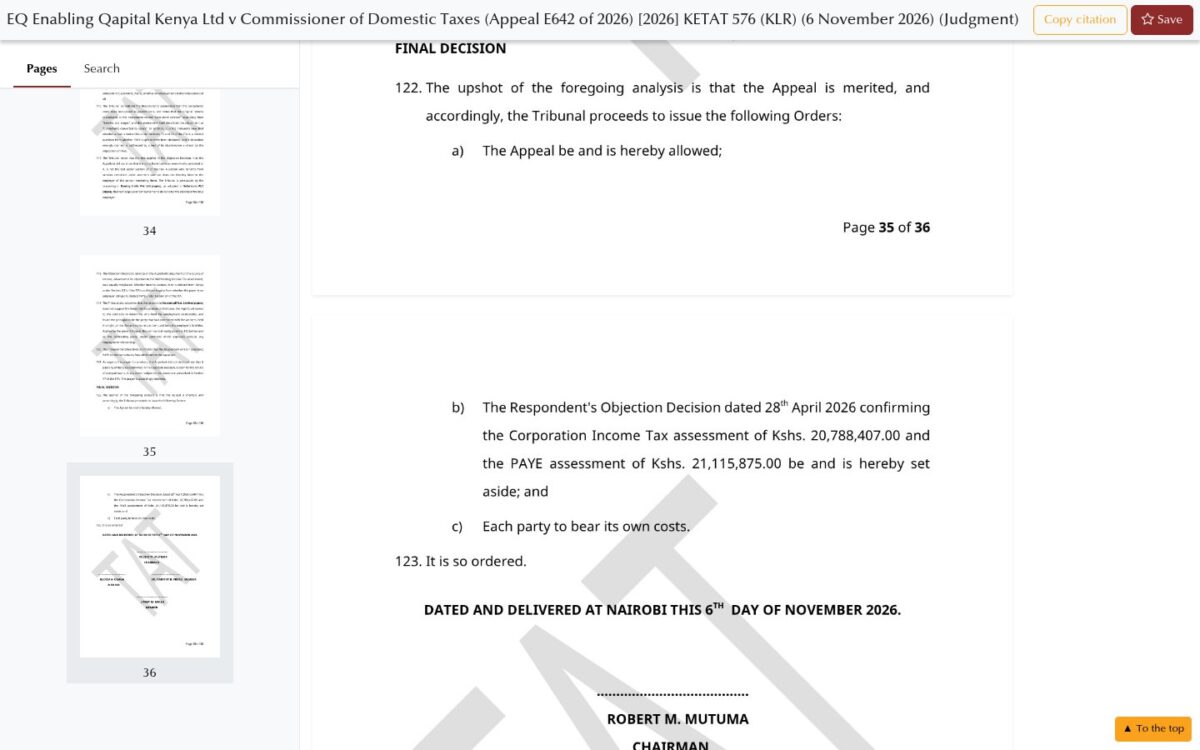
The tribunal, chaired by Robert Mutuma, delivered the judgment on 6 November 2026 in Appeal E642 of 2026. It cancelled a corporation income tax assessment of KSh20,788,407 and a PAYE assessment of KSh21,115,875, and ordered each side to bear its own costs.
On this page
How the KRA claim started
EQ Kenya was registered as a foreign company in January 2022. It gives investment advisory services to its Swiss parent, including market research, sourcing and due diligence on impact investments in Kenya and Africa.
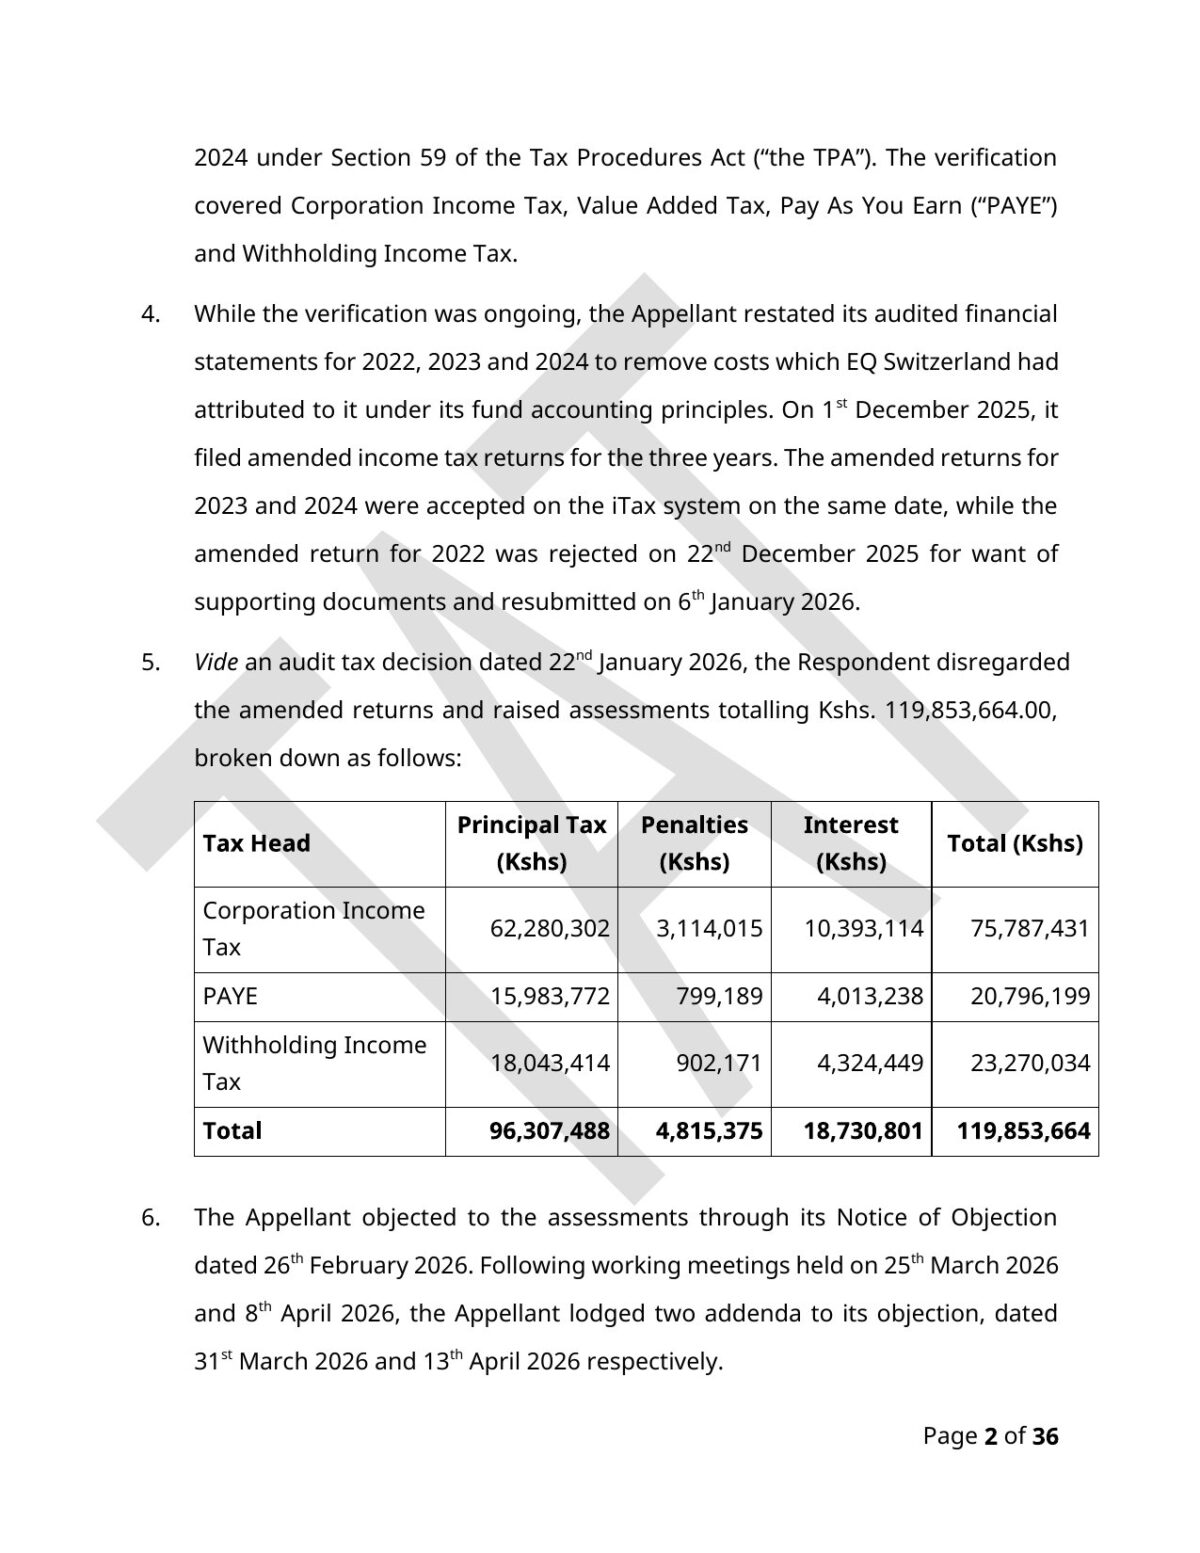
KRA began verifying its returns for January 2022 to December 2024 in May 2025. While that review was running, the branch restated its audited accounts to remove costs the parent had allocated to it, and filed amended income tax returns on 1 December 2025. iTax accepted the 2023 and 2024 amendments the same day, and the branch paid the extra tax they produced: KSh251,710 and KSh326,724.
On 22 January 2026, KRA disregarded the amended returns and raised assessments totalling KSh119,853,664, made up of corporation tax, PAYE and withholding tax plus penalties and interest. Its objection decision of 28 April 2026 dropped the withholding tax claim but kept the rest.
What the transfer pricing ruling found
The tribunal said an acceptance on iTax is the Commissioner’s acceptance under section 31(3) of the Tax Procedures Act, not “a mere administrative act”. A rejection of the 2022 amendment could not cancel the accepted 2023 and 2024 returns, and the resubmitted 2022 return was deemed accepted because KRA gave no reasons for rejecting it within 30 days.
On pricing, the branch earned a 3% mark-up on costs under the transactional net margin method. KRA applied 13% instead. The tribunal found the 13% figure “is not the product of any analysis on record”, noting KRA did no benchmarking of its own and relied on a superseded draft policy. “A superseded draft does not represent a taxpayer’s transfer pricing position,” it said.
KRA had also treated fees for consultants hired and paid by the Swiss parent as salaries of the Kenyan branch. The tribunal rejected that, saying “a person who benefits from services rendered under another’s contract does not thereby become the employer”. It declined a refund request because the branch did not show it had paid the disputed taxes.
What it means for multinationals in Kenya
The transfer pricing ruling adds to a run of tribunal decisions this month on how KRA handles group charges, including the Imperial management fees case and the Absa refund order. Firms planning amendments can read our guides on amending a KRA return and objecting to a KRA assessment on iTax.
For branches of foreign groups, the transfer pricing ruling is a reminder that KRA must back any margin it applies with its own benchmarking, and that consultants engaged and paid by a parent are not automatically employees of the local branch. KRA can still appeal to the High Court within the period set by law.
Frequently asked questions
What did the transfer pricing ruling decide?
The Tax Appeals Tribunal set aside KRA’s confirmed corporation tax assessment of KSh20,788,407 and PAYE assessment of KSh21,115,875 against EQ Enabling Qapital Kenya.
Why did KRA lose on the 13% mark-up?
The tribunal said the 13% figure was not based on any benchmarking on record, while the branch’s 3% margin sat at the median of its own policy’s range.
Can KRA ignore amended returns accepted on iTax?
The tribunal said acceptance on iTax is the Commissioner’s acceptance, so KRA must use the formal amendment procedure to displace an accepted return.
Did EQ Kenya get a refund?
No. The tribunal declined the refund request because the branch did not show that it had paid the disputed taxes.
Can KRA appeal the transfer pricing ruling?
Yes. KRA can challenge the transfer pricing ruling at the High Court within the time set by law.
Prefer WhatsApp? Follow Business Radar on WhatsApp
We will email you a weekly money and business brief. We store your email (and your name, if you give one) for that purpose, under the Kenya Data Protection Act, 2019. You can unsubscribe at any time. Privacy policy.

